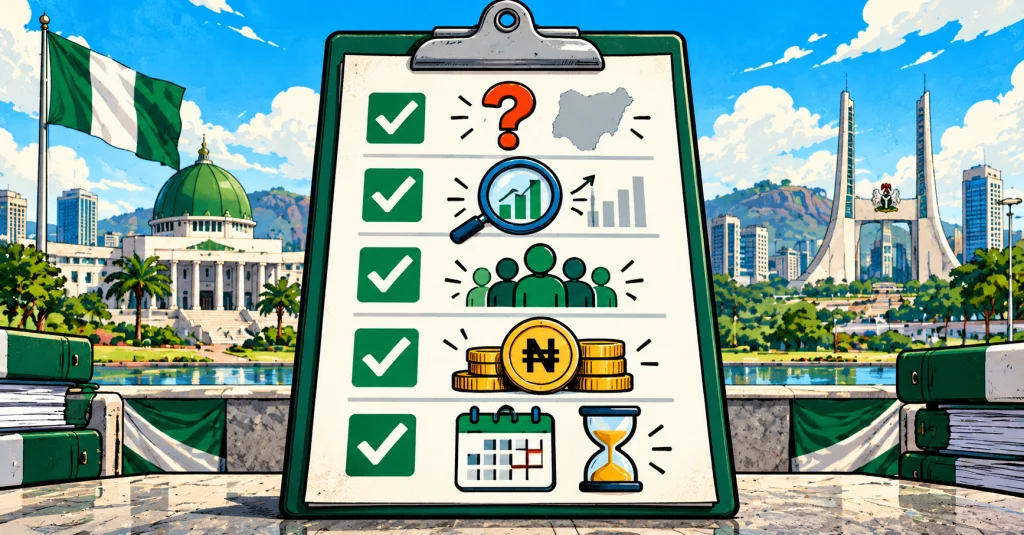
The government is proposing new rules that would require officials to identify who benefits, who pays and what a policy is expected to accomplish before putting it into effect.
In Nigeria, a government decision to change taxes, tariffs or business regulations can quickly affect the price of everyday goods, the cost of running a company and whether employers are willing to hire. Now, the government wants officials to explain the likely consequences of major economic decisions before implementing them. As TheCable reported October 26, Finance Minister Taiwo Oyedele has introduced a proposed economic policy framework intended to make government decisions more predictable and accountable.
The proposal would require major economic policies to answer five basic questions: What problem is the government trying to solve? What evidence supports the proposed solution? Who benefits? Who bears the cost? And when should the policy end? These assessments would apply to decisions involving taxation, tariffs and regulation. The goal is to reduce abrupt policy changes that leave businesses and households adjusting to unexpected costs.
Consider a government decision to increase tariffs on imported goods. Domestic manufacturers might benefit because competing foreign products become more expensive. But businesses that depend on imported materials could face higher operating costs, while consumers might pay more at the register. Under the proposed framework, officials would need to examine those trade-offs before introducing the policy, rather than leaving businesses and households to discover the consequences afterward.
The government also wants an annual economic scorecard measuring real wages, employment and poverty. Those indicators would help determine whether economic policies are improving people’s financial circumstances. Economic growth alone does not guarantee that workers earn more, jobs become more secure or families can afford basic necessities.
The proposal addresses a persistent problem for businesses: uncertainty. Companies make hiring and investment decisions based partly on expectations about future costs. Sudden changes to taxes or regulations can disrupt those plans, particularly for smaller businesses with limited financial reserves. More consistent policymaking could make it easier to plan, invest and expand.
But the framework will only matter if officials use the findings. Governments can conduct assessments and still approve policies that impose unnecessary costs or favor politically influential industries. Public access to the analysis, measurable results and clear expiration dates would make the process more meaningful.
Nigeria plans to open the proposal for public consultation on November 27. It has not yet been adopted. If implemented effectively, the framework could give businesses and households greater visibility into the decisions affecting their finances. Its real value will depend on whether government officials are willing to change course when the evidence shows that a policy creates more problems than it solves.