
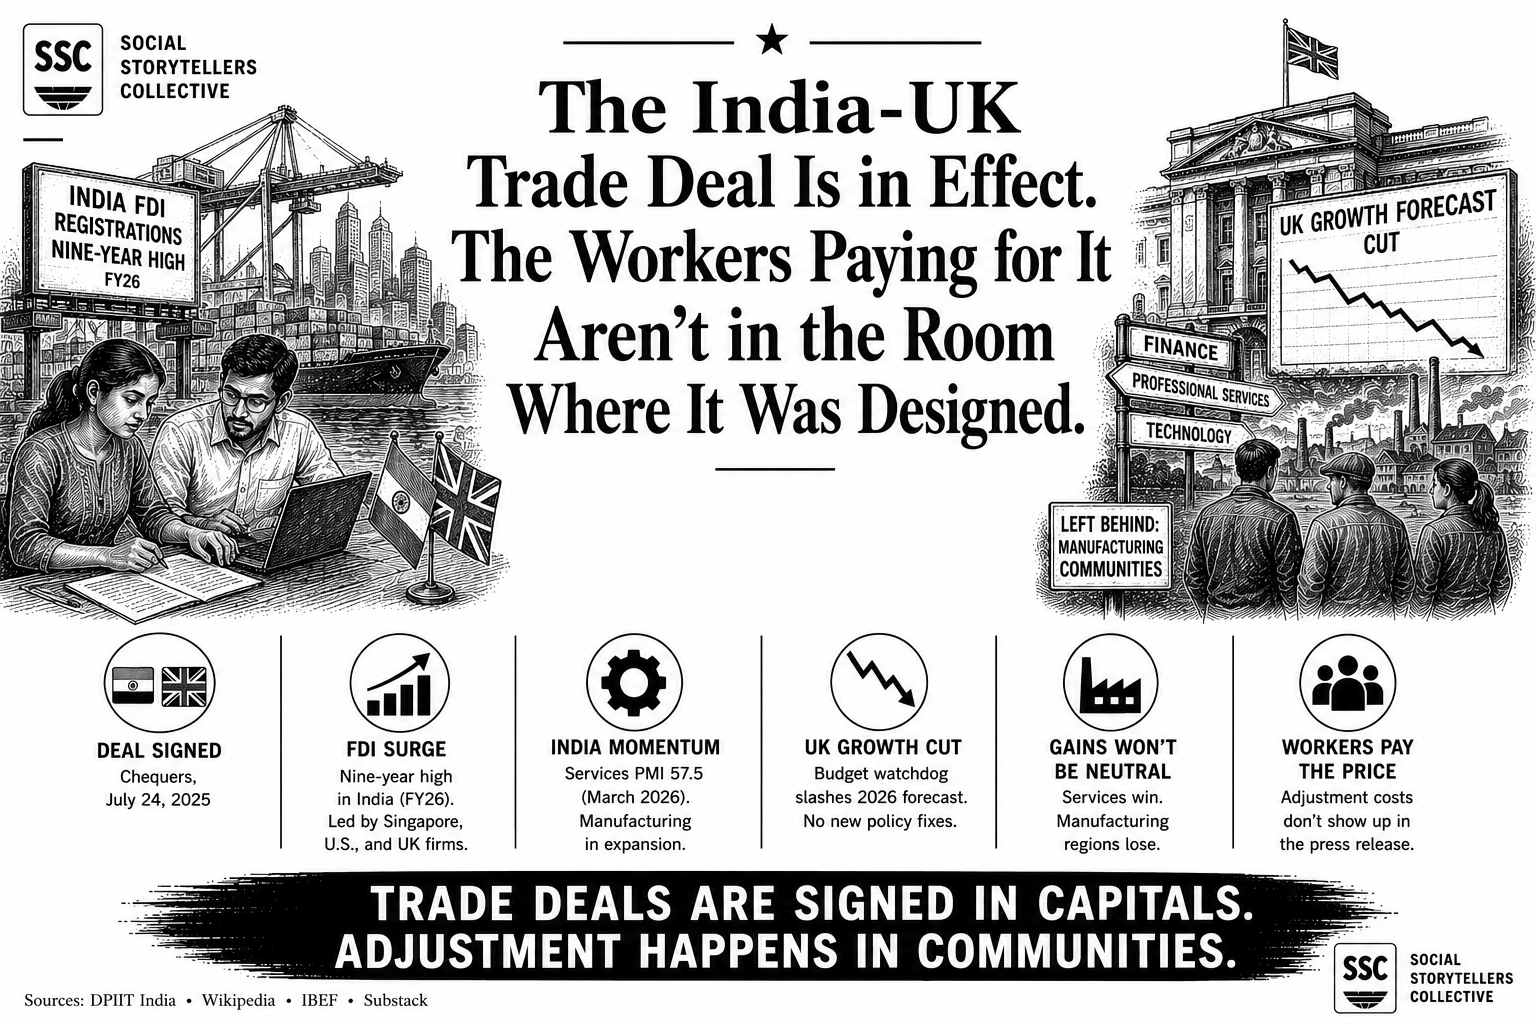
The India-UK Comprehensive Economic and Trade Agreement was signed at Chequers on July 24, 2025, by Prime Minister Narendra Modi and Prime Minister Keir Starmer, completing four years of negotiations across fourteen formal rounds. By FY26, foreign company registrations in India hit a nine-year high, led in part by firms from the United Kingdom repositioning their trade and investment relationships following the agreement. Registrations were led by firms from Singapore, the U.S., and the UK, with the trend described by India’s DPIIT as signaling “rising international confidence in India’s business environment and long-term growth potential.” India’s services PMI reached 57.5 in March 2026. Its manufacturing sector is projecting continued expansion. The deal landed at a moment when India’s fundamentals were already in motion — making the agreement less a catalyst than an accelerant for capital already looking to move.
The UK’s situation is more complicated. The 2026 UK Spring Statement, delivered by Chancellor Rachel Reeves on March 3, contained no major tax or policy changes but confirmed that the budget watchdog had slashed its forecast for UK growth in the year — with Reeves calling it nonetheless the “right economic plan.” A trade agreement with the world’s fastest-growing major economy is not a wrong decision in that context. But the distribution of its benefits inside the UK will not be neutral. The services sector — finance, professional services, technology — is positioned to capture most of the gains on the British side. The manufacturing communities in the North East, the Midlands, and Wales that have been operating in long-term deindustrialization are not the primary beneficiaries of a trade deal structured around services liberalization and professional visa mobility.
SSC has been watching the India-UK trade relationship since the agreement was signed at Chequers — and as we reported in India Just Attracted More Foreign Companies Than in Any Year Since 2017. Not Everyone Will Feel the Difference., the FDI surge is real but the distribution question remains unanswered on both sides of the deal. The historical parallel is instructive: the UK-China trade expansion of the 2000s and 2010s produced real gains in financial services and consumer goods affordability while accelerating the contraction of domestic manufacturing in precisely the regions that were already under structural pressure. The workers in those regions didn’t receive compensatory investment or retraining at the scale the adjustment required — and the political consequences of that gap contributed directly to the conditions that produced the Brexit vote. UK house prices fell fastest in London, the North East, and the North West in the year to March 2026 — regions where the trade deal’s gains are least likely to concentrate — while growing fastest in Northern Ireland, Wales, and Scotland, where demand is being driven partly by internal migration from higher-cost areas. The geographic inversion of where UK growth is happening and where trade deal benefits are expected to land is not a coincidence.
India’s nine-year-high in foreign registrations and the India-UK agreement are being framed as a bilateral success — two democracies strengthening economic ties in a realigning global order. That framing is accurate as far as it goes. What it excludes is the internal distribution question on both sides: which Indian workers in which sectors at which income levels will capture the productivity gains from expanded foreign investment, and which UK workers in which regions will absorb the adjustment costs of a trade liberalization deal designed primarily around the needs of capital that already knows how to move. The deal is signed. The negotiators have moved on. The adjustment is just beginning.