
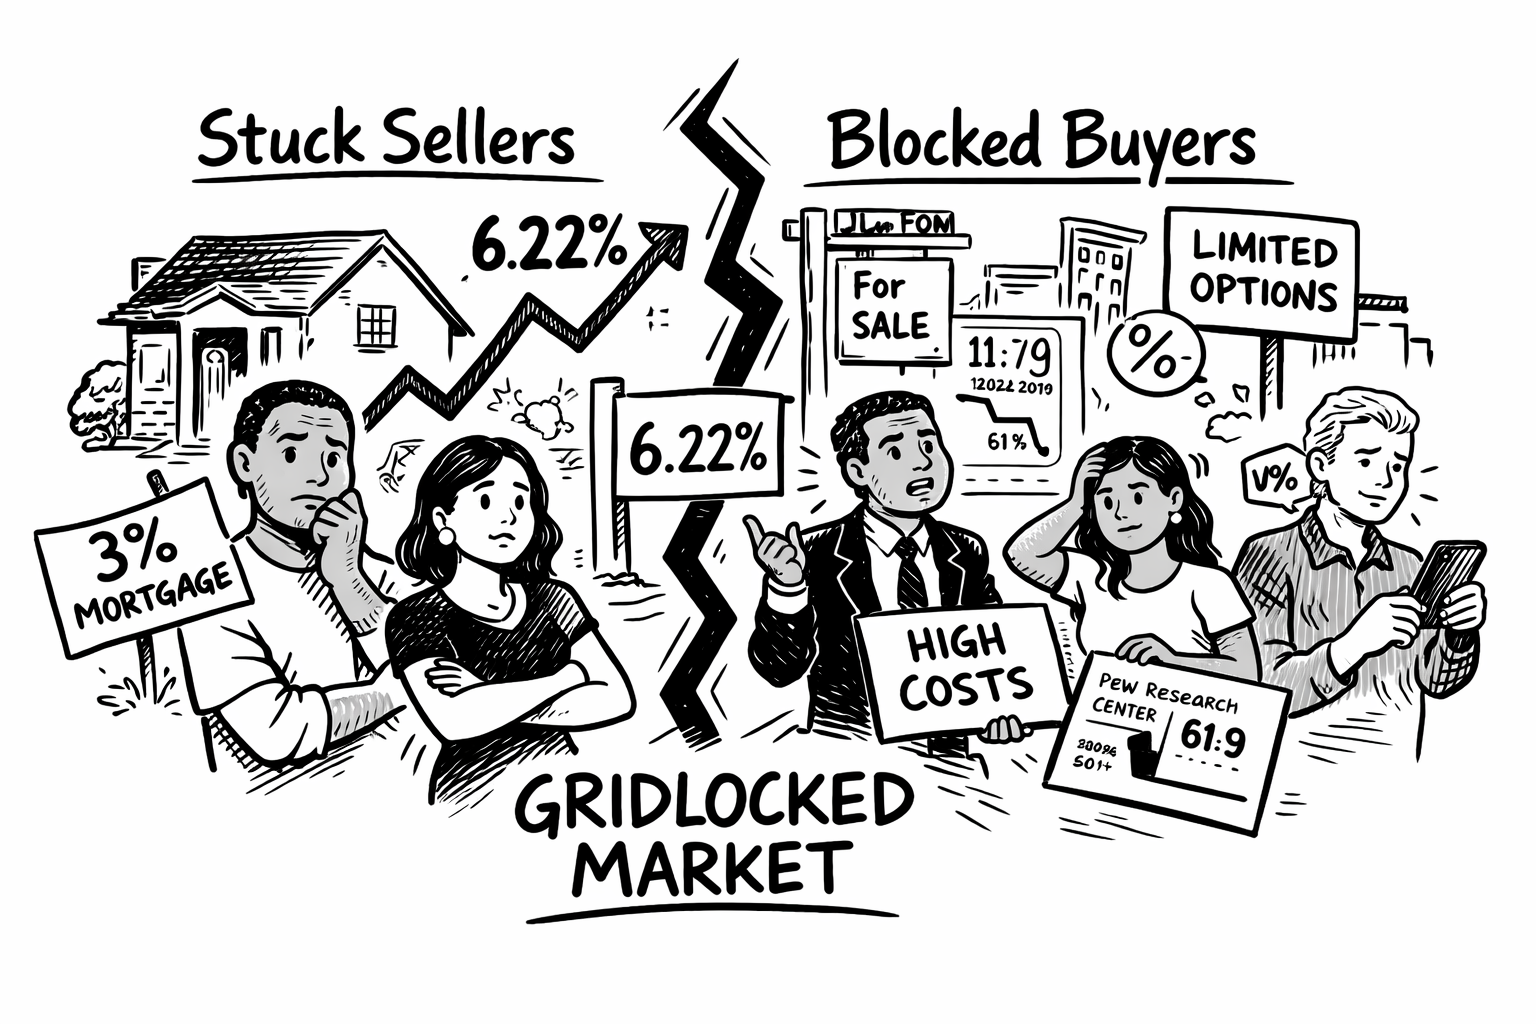
The housing market was supposed to be easing by now. Rates were projected to fall, inventory to recover, affordability to improve. Instead, the average 30-year fixed mortgage rate rose to 6.22% as of March 19 — up from 6.11% the week prior — and while active listings are up 7.9% year over year, inventory remains well below pre-pandemic norms. The market is moving. It is not loosening.
The core problem is structural. Existing homeowners locked into sub-3% pandemic-era rates have little incentive to sell, which suppresses inventory and keeps prices elevated. Prospective buyers face high financing costs, limited options, and a First-Time Buyer Affordability Index that has fallen from 111.9 in 2020 to 61.9 Pew Research Center — a collapse in purchasing power that no modest rate dip is going to fix. Meanwhile, new-home sales dropped 17.6% in January to a 587,000 annual pace, signaling that builders aren’t filling the gap either.
What makes this moment distinct is that no single factor is driving the constraint — it’s the interaction between rates, supply, and pricing that creates the sense of immobility. Addressing one in isolation doesn’t resolve the broader issue. It’s a self-reinforcing system, and it’s squeezing hardest at the entry level. As we explored in Stability, Pending Approval, the affordability crisis isn’t abstract — it’s reshaping where people live, how long they rent, and whether homeownership remains a realistic milestone at all.
The housing market isn’t broken. But for most buyers, it’s beginning to feel that way.