
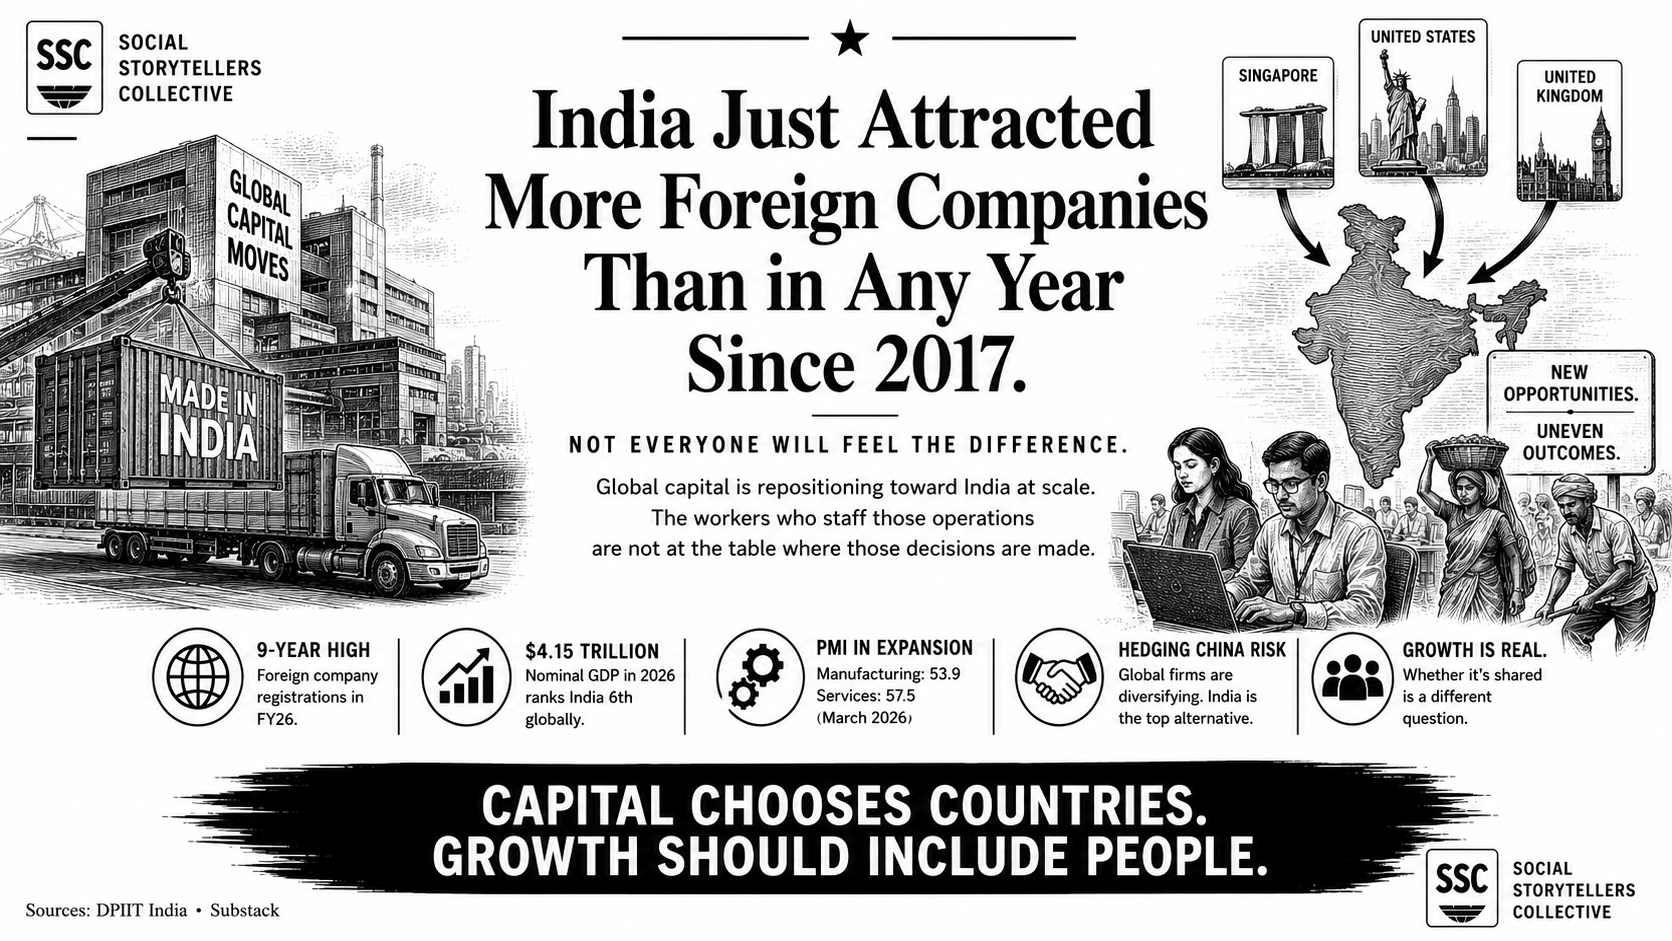
Foreign company registrations in India hit a nine-year high in FY26, led by firms from Singapore, the United States, and the United Kingdom — a signal, according to India’s Department for Promotion of Industry and Internal Trade, of rising international confidence in the country’s business environment and long-term growth potential. India’s GDP reached $4.15 trillion nominal in 2026, placing it sixth globally, while its PPP-adjusted GDP of $18.90 trillion ranks it third in the world. India’s manufacturing PMI hit 53.9 in March 2026, and the services PMI reached 57.5 — both in sustained expansion territory, with the services sector accounting for 54.7% of GDP. The numbers are real, and they are attracting capital at a pace that suggests this isn’t a cyclical surge. It is a structural repositioning.
The context for that repositioning is explicit: global firms are hedging their China exposure. Regulatory pressure, supply chain disruption, and geopolitical risk calculations have been pushing multinational capital toward alternative manufacturing and services bases for several years. India is the largest and most institutionally stable of those alternatives — a democracy with a skilled technical workforce, a maturing regulatory environment, and a government that has made foreign direct investment attraction a central policy priority. The nine-year high in foreign registrations was led specifically by firms from Singapore, the U.S., and the UK — economies with deep existing trade relationships — following the India-UK Comprehensive Economic and Trade Agreement signed in July 2025, which created new access frameworks for both goods and services. The trade architecture is being built in real time around capital that has already decided to move.
The structural pattern this mirrors is Southeast Asia in the 1990s and early 2000s — the period when global manufacturing capital relocated to Vietnam, Thailand, and Indonesia in search of lower costs and more favorable regulatory environments. The gains from that repositioning were real and generated genuine economic growth in receiving countries. The distribution of those gains — which workers in which regions in which sectors captured them, and at what labor conditions — was a separate and often disappointing story. India’s $2,813 GDP per capita in nominal terms in 2026, against a $12,964 PPP equivalent, signals the gap between the aggregate growth story and the ground-level reality for workers not positioned to capture the premium end of services expansion. India’s cement industry is projecting 7–8% growth in FY27, driven by infrastructure and housing demand, with major producers accelerating capacity expansion — but cost pressures from geopolitical uncertainties tied to the West Asia conflict are compressing margins across the supply chain.
What the foreign registration data reflects is investor confidence in India’s institutional framework — its legal system, its regulatory environment, its workforce depth. What it doesn’t capture is the internal geography of that confidence: the difference between Bangalore’s services economy and Bihar’s agricultural one, between the engineers being recruited into multinational technology operations and the informal workers whose labor underpins the infrastructure those operations depend on. Capital moves to India as a country. It lands in specific cities, specific industries, and specific income brackets. The India-UK trade agreement, the FDI surge, and the PMI expansion are all real indicators of a structural shift in where global capital is positioning. Whether the communities that have historically been excluded from India’s growth story — by caste, by geography, by gender, by sector — will be included in this cycle is a question the headline numbers don’t answer.